China Aromatic Carbonyl Intermediate Applications and Market Dynamics
2026-09-25
China's aromatic carbonyl intermediates rarely dominate headlines, yet they shape a surprising range of industries—from pharmaceutical synthesis and agrochemical actives to high-performance fragrances and specialty polymers. As domestic capacity expands and environmental regulations tighten, the market is undergoing a quiet but significant recalibration. Understanding where applications are heading and how supply dynamics are shifting has become critical for buyers and formulators. DSL Chemicals tracks these developments in real time, helping you turn market complexity into confident sourcing decisions.
The Quiet Backbone of Pharma and Agrochemical Synthesis
Behind every launched pharmaceutical or crop protection product sits a layer of synthesis that rarely gets named in press releases: the intermediates and building blocks. Chiral amines, halogenated heterocycles, substituted pyridines—these are the molecules that determine whether a route stays within cost targets, hits purity specs, or even survives scale-up. They don't appear on the label, but without them the final active ingredient simply cannot be made.
The quiet part of this work is not just making the compounds, but making them reliably at kilogram to multi-ton scale. A trace impurity in an agrochemical intermediate can shift field trial results, while a single stereocenter gone wrong in a pharma building block can sink an entire development program. The effort often goes into stubborn selectivity problems: finding a route that avoids protecting groups, cuts out cryogenic steps, or swaps an expensive chiral pool starting material for something the plant can actually handle.
As supply chains become less forgiving and regulatory thresholds tighten, these behind-the-scenes building blocks carry more weight than ever. Teams that can deliver complex intermediates with consistent enantiomeric excess, low residual metals, and clean impurity profiles give drug and agrochemical developers the freedom to focus on biology and field performance—without quietly wondering whether the chemistry will fall apart when it matters most.
Shifting Capacity and Trade Flows Along the Yangtze
The Yangtze River has long been the spine of China's inland logistics, but its carrying capacity has never been a fixed figure. Over the past decade, dredging campaigns and lock expansions along the middle and upper reaches have quietly rewritten what vessels can move. A barge that once stopped at Wuhan now pushes past the Three Gorges with heavier drafts, and that physical change ripples through every port ledger downstream. Capacity is not just about deeper channels; it is about how many days a shipment can avoid sitting idle at a congested transfer hub.
Trade flows respond to these shifts in ways that are rarely linear. When Chongqing can reliably send containerized electronics eastward without transshipment, the calculus for manufacturers in Sichuan and Guizhou changes. Rail and road corridors still compete, but for bulk commodities like steel coil or grain, the river often wins on cost per ton-mile once the draft allows larger convoys. The result is a quieter, more persistent realignment: upstream cities gain direct export links, while traditional gateway ports like Nanjing and Shanghai adjust their roles from sole handlers to strategic chokepoints and value-added service centers.
Seasonal variability adds another layer. Low-water months still expose bottlenecks, but improved forecasting and water-release coordination with the Three Gorges Dam have smoothed some of the old unpredictability. Shippers now plan around a known range of draft limits rather than sudden closures, which encourages longer-term contracts and larger inventory buffers at key terminals. In that sense, the Yangtze's shifting capacity is not just an engineering metric; it is a force that reshapes sourcing decisions, warehouse locations, and the internal geography of China's trade.
Catalytic Innovation Redefines Cost Curves
Most cost reductions follow a predictable path: incremental scale, marginal process tweaks, negotiated supplier discounts. Catalytic innovation breaks that logic. It doesn't shave a few percentage points off a curve; it bends the curve downward by changing the underlying production assumptions, material inputs, or delivery model. When a new architecture eliminates a major assembly step, or a feedstock shift removes an entire purification train, the result is not a movement along the existing cost curve but a shift to a different curve altogether.
This redefinition often looks irrational from inside the incumbent frame. The new approach carries lower theoretical limits because it sidesteps legacy constraints—physical infrastructure, labor intensity, or supply chain bottlenecks that incumbents treat as fixed. Over time, the innovator's cost curve becomes the reference point. Competitors who keep optimizing the old curve find their best possible costs still sit above the new entrant's starting point, making catch-up economically impossible without adopting the same catalytic logic.
What makes the shift durable is that it resets expectations for everyone downstream. Buyers recalibrate procurement targets, financiers re-underwrite project risk, and adjacent suppliers reprice their own contributions. The original innovation may be a single breakthrough, but the cost-curve redefinition ripples outward until the entire value chain has been re-anchored to the new economics.
Downstream Pull from Coatings and Electronic Chemicals
Demand from coating and electronic chemical producers rarely follows a straight line. A sudden jump in architectural repaint activity can pull resin inventories down within weeks, while a single smartphone launch cycle may drain specialized solvents and photoresist precursors even faster. These downstream signals travel upstream through distribution channels, forcing raw material suppliers to adjust production schedules on short notice.
The pull effect is especially visible when downstream players shift formulation strategies. A move toward low-VOC coatings, for example, triggers an immediate need for alternative coalescents and reactive diluents. Electronic chemicals show a similar pattern—new chip architectures or advanced packaging techniques often require ultra-high-purity etchants and CMP slurries that were barely on the radar six months earlier. Suppliers who monitor these shifts closely can build inventory buffers without overcommitting to fading specifications.
What makes this downstream pull difficult to manage is the mismatch in lead times. Coating manufacturers can often switch raw material grades within a quarter, but upstream producers of specialty monomers or fluorinated solvents may need nine to twelve months to expand capacity. That gap creates recurring squeeze points, particularly when several downstream segments recover at the same time. Successful suppliers treat downstream pull not as a forecast problem, but as a continuous sensing exercise—one that relies on direct conversations with formulators, not just monthly sales data.
Regulatory Pressures Reshape Production Footprints
Tariffs and carbon border adjustments have turned once-stable manufacturing maps into something far more fluid. For years, companies chased the lowest labor costs without much thought to where regulations might bite. Now a patchwork of local content rules, emissions caps, and import restrictions is forcing boardrooms to weigh compliance risks as heavily as logistics expenses. A factory that looked perfect on paper three years ago might now carry penalties that erase any margin advantage.
The shift isn't limited to any single sector. Electronics brands are quietly splitting final assembly across multiple countries to avoid sudden duty hikes, while automotive suppliers are adding regional stamping and battery plants to satisfy local sourcing quotas. Pharmaceutical producers, nudged by supply chain security laws, are bringing more API manufacturing back to North America and Europe. These moves often come with higher operating costs, but they buy something increasingly valuable: the ability to keep selling when rules tighten overnight.
Over time, this pressure is producing networks that are less centralized and more attuned to regulatory boundaries. Companies are investing in flexible lines and digital tools that let them shift production between sites without massive retooling. The goal is no longer just efficiency; it's staying on the right side of a growing stack of trade and environmental mandates while still serving customers quickly.
Price Signals and Inventory Cycles in a Maturing Market
In a maturing market, price movements carry a different weight than they do during rapid expansion. A drop in unit price rarely signals a sudden collapse in demand; more often it reflects a buildup of unsold stock somewhere along the chain. Suppliers watch competitor discounting and order backlogs closely, treating small price adjustments as early warnings rather than standalone events.
The inventory cycle tends to soften as a market matures, but it doesn't disappear. When prices firm up, producers add capacity and distributors pad their warehouses, expecting the trend to continue. Once demand settles at a lower growth rate, those extra units take longer to clear, and price concessions follow. Because buyers in such markets are less likely to rush in on price dips, the correction is slower and shallower than in younger industries.
Experienced operators learn to read the gaps between posted prices, actual transaction prices, and delivery lead times. A widening discount from list price, combined with rising days of inventory on hand, usually marks the late stage of an accumulation phase. Companies that adjust production schedules or procurement commitments before the cycle turns are the ones that avoid the worst of the margin squeeze.
FAQ
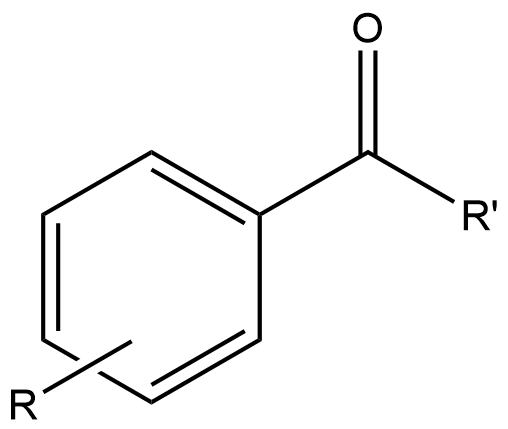
These compounds feed directly into pharmaceutical synthesis, especially for NSAIDs, antihistamines, and cardiovascular drugs, where intermediates like acetophenone and p-hydroxybenzaldehyde act as core building blocks. Agrochemical production is equally reliant, using them for herbicides and fungicides. The flavor and fragrance sector consumes large volumes for vanillin, ethyl vanillin, and heliotropin, while UV-curable coatings and photoinitiator systems have become a fast-growing outlet in recent years.
Since the nationwide environmental inspections intensified, many small and mid-sized producers lacking proper wastewater and gas treatment were shut down or forced to suspend operations. This squeezed supply for several commodity intermediates and pushed production toward larger, compliance-ready facilities in Shandong, Jiangsu, and Hebei. The result has been higher industry concentration, more stable quality from surviving players, and occasional price spikes when a major plant undergoes rectification.
Benzaldehyde, acetophenone, p-hydroxybenzaldehyde, and anisic aldehyde are the workhorses of export. Chinese producers benefit from integrated toluene and benzene supply chains, mature oxidation and chlorination processes, and lower labor and utility costs. Buyers in India, Europe, and North America often source these intermediates because Chinese suppliers can deliver consistent purity at prices that undercut local production, particularly for bulk pharmaceutical and fragrance grades.
They are indispensable in constructing active pharmaceutical ingredients. Acetophenone derivatives are used to build ibuprofen and other anti-inflammatory agents, while p-hydroxybenzaldehyde is a key precursor for antibiotics and certain cardiovascular drugs. Anisic aldehyde feeds into antihistamine and anti-allergy syntheses. Domestic API manufacturers increasingly demand higher-purity, low-impurity intermediates because downstream formulation standards and export audits have become stricter.
Demand is shifting from low-cost, commodity-grade material to customized, high-purity, and sometimes chiral intermediates. The domestic pharmaceutical and pesticide sectors are expanding their own API and formulation capacity, pulling more intermediate consumption. At the same time, the food-grade flavor market is growing as consumers favor natural-identical vanillin and ethyl vanillin, pushing producers to upgrade purification and meet stricter residual solvent limits.
Shandong, particularly around Weifang and Zibo, dominates in benzaldehyde and acetophenone because of proximity to toluene and chlorine sources. Jiangsu and Zhejiang focus more on fine and pharmaceutical-grade products, leveraging stronger R&D and custom synthesis capabilities. Hebei and Liaoning host cost-driven operations with simpler derivatives. Each hub has distinct strengths: Shandong for scale, Jiangsu/Zhejiang for high-end quality, and the northern provinces for low-cost bulk supply.
Toluene and benzene are the primary feedstocks, so any crude oil or aromatics price movement immediately hits production costs. Producers often use annual or quarterly contracts with petrochemical suppliers to smooth volatility, but sudden spikes still squeeze margins because downstream buyers resist rapid price increases. Larger players invest in catalyst improvements and continuous processing to raise yield per ton of feedstock, while smaller ones may simply idle capacity during periods of high raw material cost.
Continuous-flow oxidation and greener catalytic air oxidation for benzaldehyde are replacing older chlorination-hydrolysis routes, cutting waste and improving safety. Several firms have expanded p-hydroxybenzaldehyde and anisic aldehyde lines to meet rising export and domestic pharmaceutical demand. There is also a visible shift toward integrated production, where the same site handles the basic aromatic oxidation and subsequent derivatization, reducing intermediate storage and transport risks.
Conclusion
China's aromatic carbonyl intermediates rarely attract much attention, yet they sit at the heart of countless pharmaceutical and agrochemical syntheses. Along the Yangtze River, production capacity is quietly being redistributed—older, less efficient plants are being replaced by larger, integrated sites that can better manage feedstock costs and waste streams. This shift is not just about scale; catalytic innovation has started to rewrite the economics. Newer oxidation and carbonylation routes allow producers to trim variable costs by double digits in some cases, which in turn puts pressure on competitors running legacy processes.
Beyond pharma and agrochemicals, coatings and electronic chemicals are pulling more volume into the market, creating demand that is less seasonal and more tied to industrial output. Regulatory pressure, especially around emissions and water use, has forced a rethink of production footprints—some capacity has moved inland or to designated chemical parks, while marginal operators have exited. As the market matures, price signals have become sharper and inventory cycles more measured. Buyers and sellers now respond faster to feedstock swings, but the overall pattern remains cyclical, with periodic tightness followed by deliberate destocking. The result is a sector that is more consolidated, cost-conscious, and quietly central to downstream chemistry.
Contact Us
Contact Person: Wei Zhang
Email: [email protected]
Tel/WhatsApp: 862163529955
Website: https://www.dslchem.com